A one-time financial plan, yours to keep
A detailed financial plan that is yours to keep, without the long-term commitment. Perfect for people at a financial turning point that want an expert's review, but who prefer to manage their own finances long-term.
One plan, one engagement
A turning point in your financial life
A job change, a growing family, the years before retirement, a portfolio review, or an equity compensation decision; these can all raise questions that benefit from a full look at your situation.
You want advice, but want to stay in control
You would like a detailed written plan to take home and work from, and you are comfortable carrying it out yourself without ongoing management.
You have specific questions
You want focused answers on a decision or a set of decisions, without signing up for a long-term relationship.
Four steps, start to finish
- 01
Initial call
A conversation to learn about your situation and what you want to get out of the project.
- 02
Client information intake
You share the details of your financial picture and future goals, so the plan is built on your actual circumstances. This can be done digitally and usually takes clients ~30 minutes.
- 03
Detailed plan review
Your advisor prepares your written plan and walks you through it, including the reasoning behind each part and the trade-offs involved. The finished plan is yours to keep.
- 04
Follow-up meeting
One follow-up meeting for implementation and any clarification, available at any point during the six months after your plan review.
Your plan, in detail
Areas covered will be different for everyone, but these examples show the kind of planning outputs you may see.
Your goals, on your terms
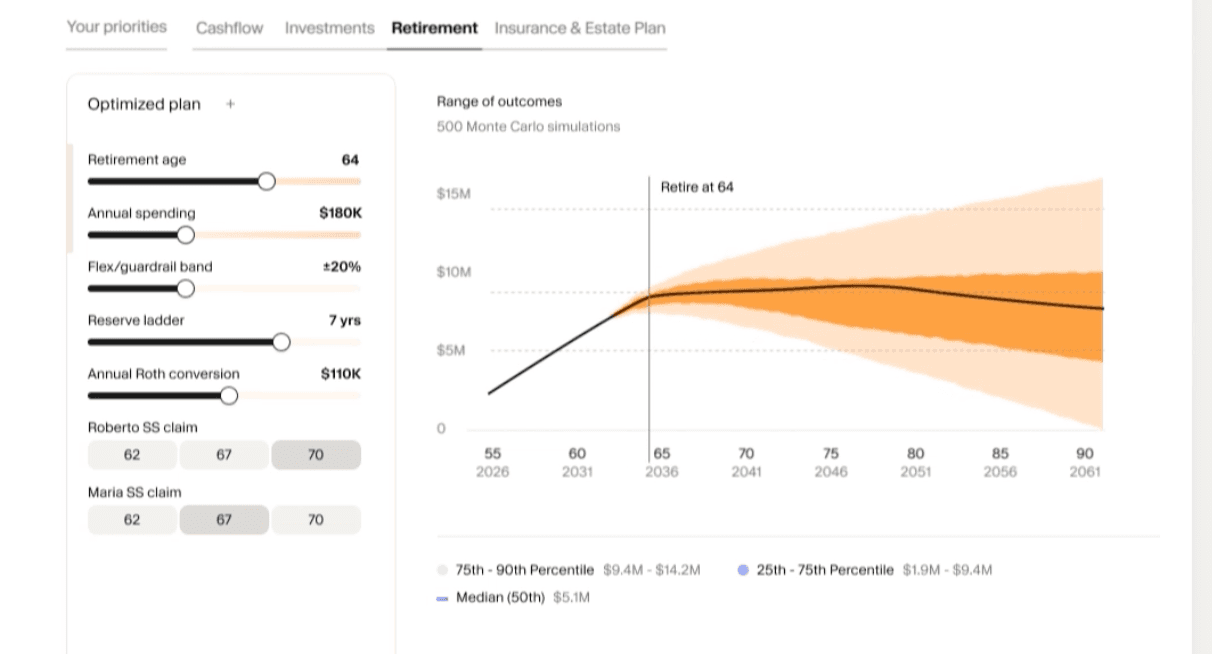
A plan should start with your goals, including when and how you might retire, what are you building towards, how and when you want to support dependents, and much more. We'll map how a range of scenarios, timing, and market conditions could impact your odds of success. You can leave confident that your goals are the right ones, with the clear roadmap to get there.
Mapping every dollar
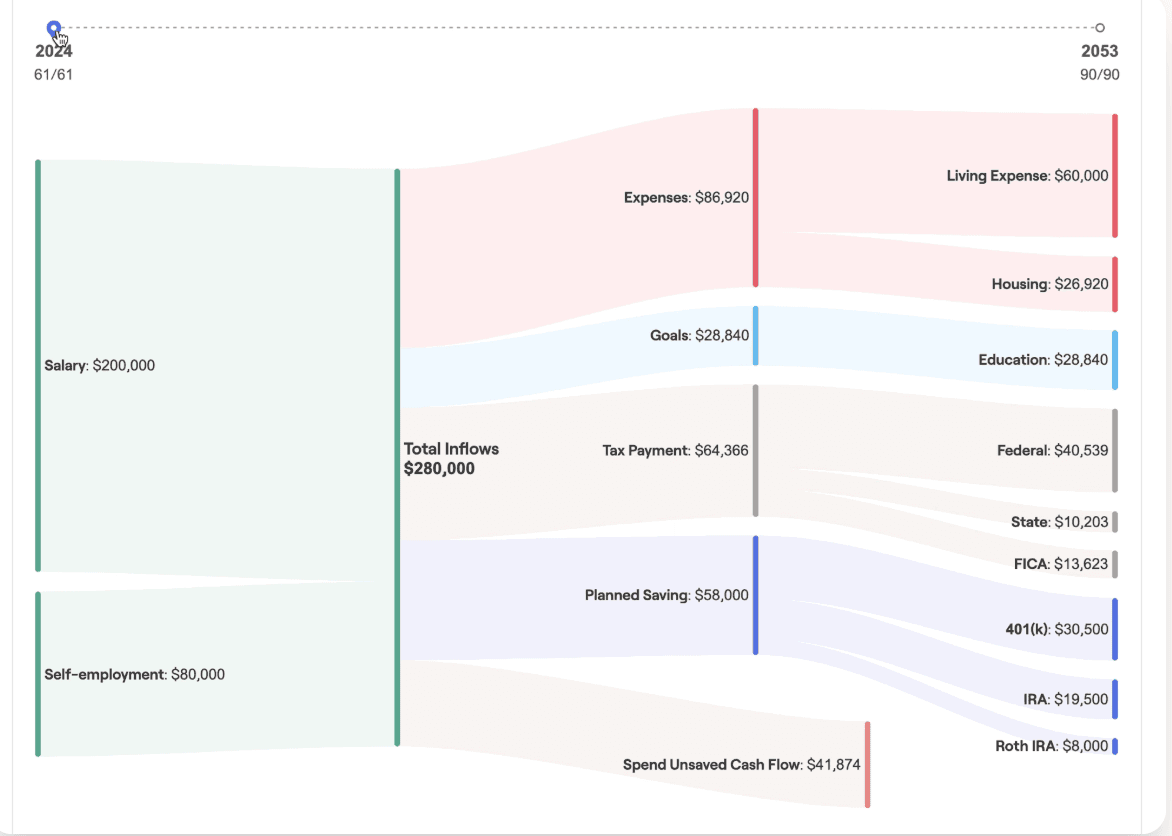
Your plan can map income against spending year by year, including planned one-time costs, and map every dollar so you know which accounts to fund, and when, to optimize for your goals.
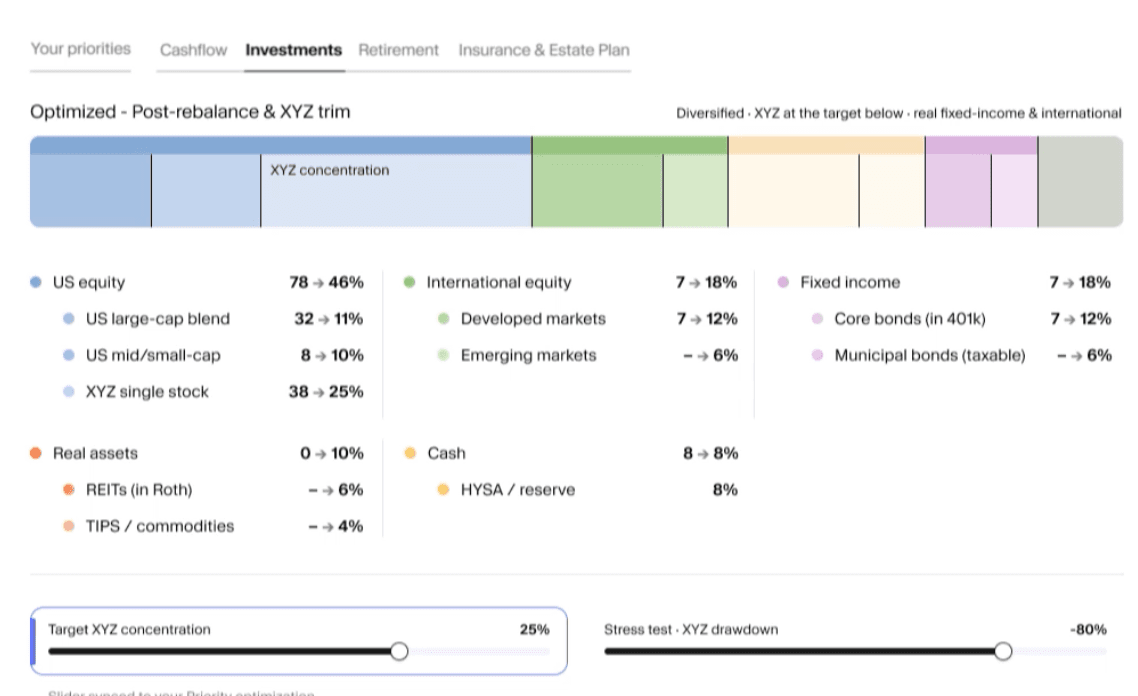
Investments
A plan can review how your investments are allocated and where risk may exist. We'll talk through allocation, asset location, diversification, and how all of this may impact your taxes, and you'll leave with a detailed set of investment options to execute.
Insurance review
We'll look at more than just investments. A plan can review your existing coverage and look at how a gap could affect the people who depend on you.
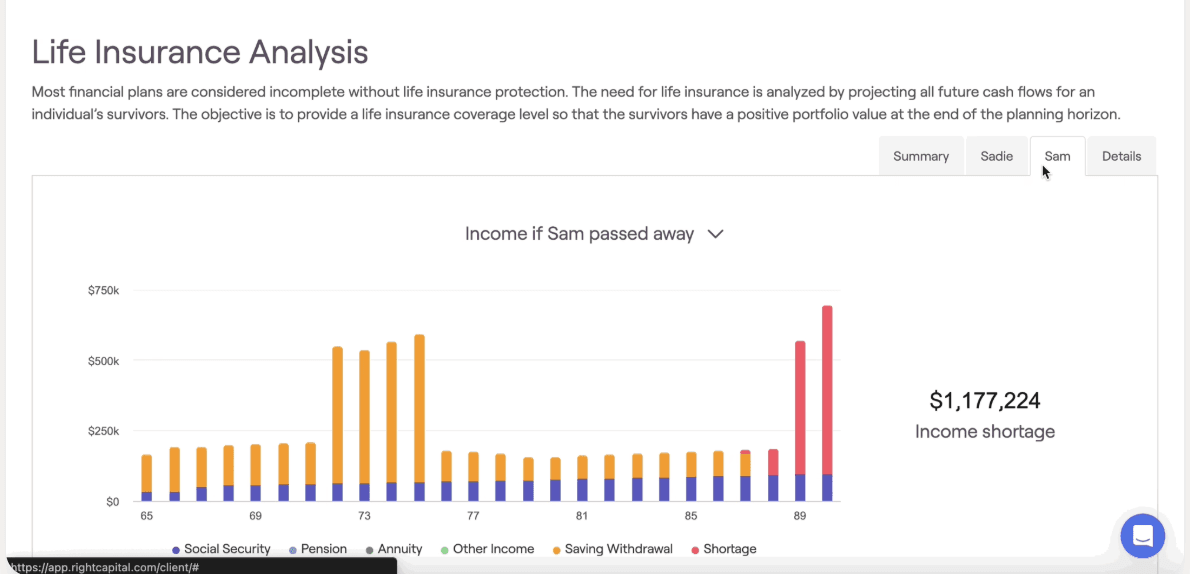
Important: The images on this page are illustrative examples only. They are hypothetical, do not show actual client data, and are not a projection or guarantee of results for any investor. Projections depend on assumptions that may not hold, actual results will differ, and every plan is based on an individual's own circumstances. This page is general education and is not personalized investment, tax, or legal advice.
Equity comp and tax strategy
If you work at a startup or a tech company, equity compensation can add decisions that a standard plan may not cover. Options, RSUs, and ESPP purchases are taxed and timed differently, and the tax bill for one decision can depend on the rest of your income that year. A one-time plan can look at these pieces together.
Common decision points include:
- When to exercise stock options, and how much cash that may require.
- Whether to sell or hold shares after RSUs vest or an employee stock purchase plan (ESPP) buys.
- Whether an 83(b) election applies to your grant. This election is time-sensitive, so it is worth raising with a tax professional early.
- How exercising incentive stock options may interact with the alternative minimum tax (AMT).
- How much of your net worth is tied to one employer, and how that fits your cash needs and goals.
These are critical decisions to make before the liquidity event, not after.
A flat fee, paid once
One-time financial plan
$2,500
One-time fee
Includes the initial call, client information intake, detailed plan review, and one follow-up meeting for implementation and any clarification, available for six months after your plan review. Your written plan is yours to keep.
Optional add-on: Trust & Will
+$250
Added to the project fee
Includes creation of a revocable trust and a pour-over will through Trust & Will. LKL Advisors has no direct relationship or revenue-sharing arrangement with Trust & Will. We do not provide legal advice or draft legal documents; for legal questions, consult a licensed attorney.
After your plan
Two optional add-ons are available at any point to anyone who has completed a full plan with us at some point.
Optional add-on: Full plan update
$2,000
Discounted from the $2,500 project fee
A refresh of your full plan when your circumstances, goals, or assumptions have changed. Available at any point after your original plan.
Optional add-on: Ad hoc strategy calls
$500
Per call
A call to work through one specific topic, such as an upcoming equity compensation decision, with targeted advice on that topic. It is not a full plan update.
If you decide to continue
If you choose to become an ongoing wealth-management client at the end of the project, your advisory fees for the first year are waived. Continuing is optional, and there is no obligation to do so. Your written plan is yours to keep either way.
See our full services and published pricing for how ongoing planning works.
What to keep in mind
- You carry out the plan yourself. This engagement does not include ongoing investment management or ongoing monitoring.
- Your written plan is yours to keep. It reflects the information you provide and the assumptions in place on the date of your plan review, and both can change over time.
- The follow-up meeting is available for six months after your plan review.
- Becoming an ongoing client after the project is optional. See our services and published pricing for how ongoing planning works.
Common questions
It may fit people at a financial turning point who want a detailed plan or answers to specific questions, and who generally prefer to manage their own finances rather than enter a long-term relationship.
An initial call, a client information intake, a detailed plan review, and one follow-up meeting for implementation and any clarification. The follow-up meeting is available during the six months after your plan review. You receive your written plan to keep.
Yes. Your written plan is yours to keep, whether or not you become an ongoing client. It reflects your information and assumptions as of the date of your plan review, so it may need updating if your circumstances, goals, or tax rules change.
It may. A plan can look at how a decision such as exercising options or selling vested shares fits your cash needs, taxes, and goals. Each choice involves trade-offs, tax rules change, and outcomes depend on your individual circumstances. A tax professional can confirm how the rules apply to you.
At LKL Advisors, the fee is a flat $2,500 for the project. You can add a revocable trust and pour-over will through Trust & Will for an additional $250. Fees and what is included vary by firm, so compare the scope as well as the price.
It depends on your situation. A one-time plan may be useful if you are at a turning point, want a detailed review, and are comfortable carrying out the plan yourself. It may be less useful if you want ongoing implementation and monitoring, or if your circumstances change often, since a plan reflects the date and assumptions in place when it is prepared.
It includes creation of a revocable trust and a pour-over will through Trust & Will. LKL Advisors has no direct relationship or revenue-sharing arrangement with Trust & Will. We do not provide legal advice or draft legal documents, and whether these documents fit your situation is a question for a licensed attorney.
Yes, if you have completed a full plan with us at some point. A full plan update is available at any point for a discounted $2,000, and an ad hoc strategy call for a specific topic is $500. The strategy call is targeted to one topic and is not a full plan update.
If you choose to become an ongoing client at the end of the project, your advisory fees for the first year are waived. Continuing is optional, and there is no obligation to do so.
Not as part of this engagement. The project is one-time and does not include ongoing investment management or monitoring. If you would like ongoing support, you can book a call to discuss whether it fits your situation.
Talk through whether a project fits your situation
Important disclosures
The charts, screens, and other visuals on this page are illustrations from financial planning software that is unaffiliated with LKL Advisors. They are provided for illustration only and do not represent actual client data. Names, figures, and scenarios shown are examples. The software's layout, features, assumptions, and outputs may differ from what you receive as a client.
Projections, simulations, and scenario analyses, including any range of possible outcomes, are hypothetical. They depend on assumptions about markets, inflation, taxes, spending, and other factors that may not hold. They do not reflect actual results, are not guarantees or predictions, and are not a projection of results for any investor. Actual results will differ, and may be lower than illustrated.
Investing involves risk, including the potential loss of principal. Diversification does not ensure a profit or protect against loss. Any allocation or concentration figures shown are examples and are not recommendations.
The tax chart is a simplified illustration. Tax rates, brackets, and rules change over time and may not match current law or your own tax situation.
The insurance analysis is an illustration of how a needs analysis may be presented. It is not a recommendation to buy or change any coverage and is not an offer to sell insurance. Coverage decisions depend on cost, eligibility, policy terms, and your individual circumstances.
LKL Advisors does not provide formal accounting or legal advice. Content on this page is general education. Please consult a qualified accountant or tax professional and a licensed attorney about your specific situation, including any decision about wills, trusts, or other legal documents.